Core Protections Against Bodily Injury and Property Damage
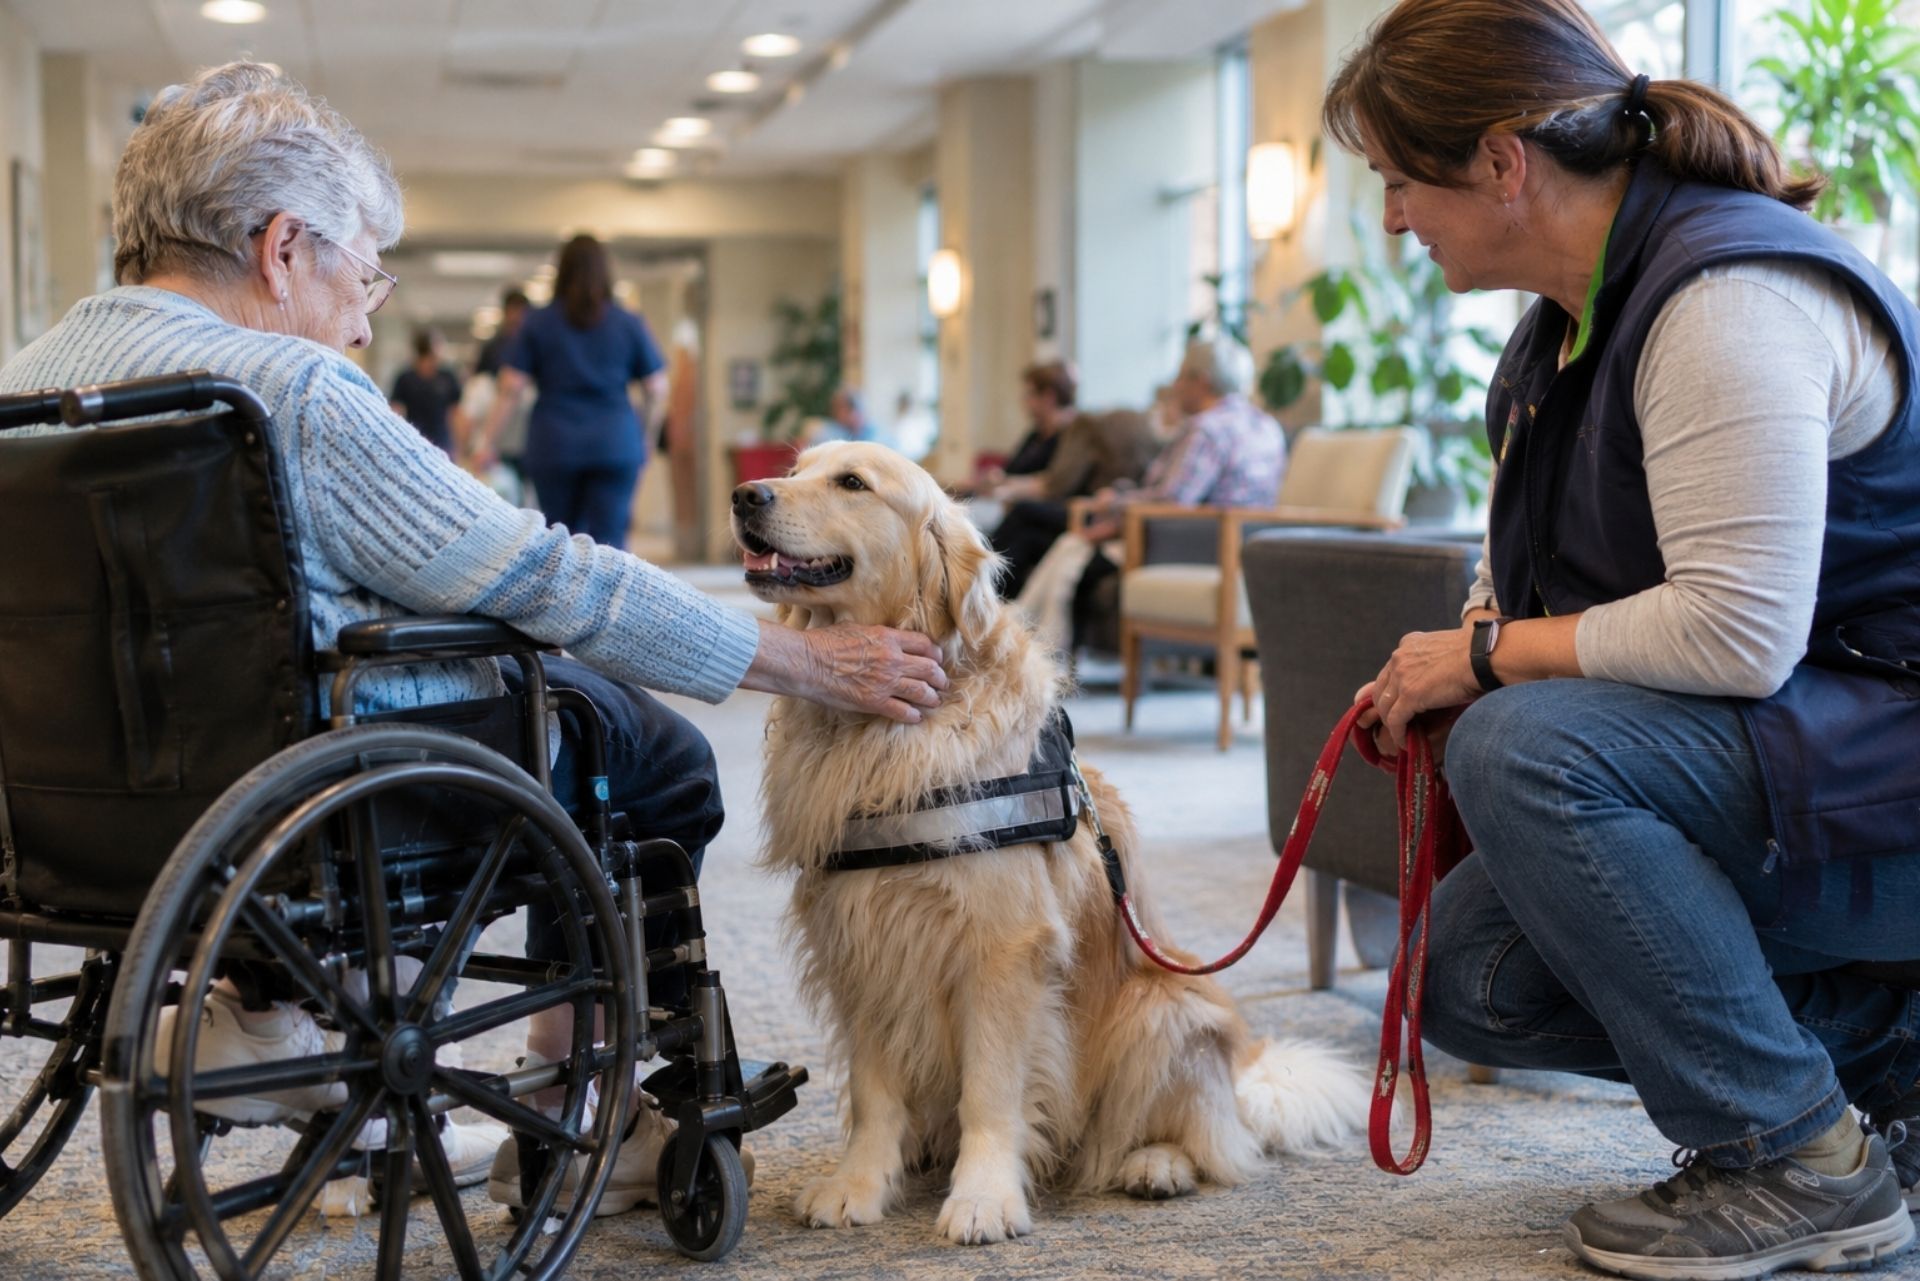
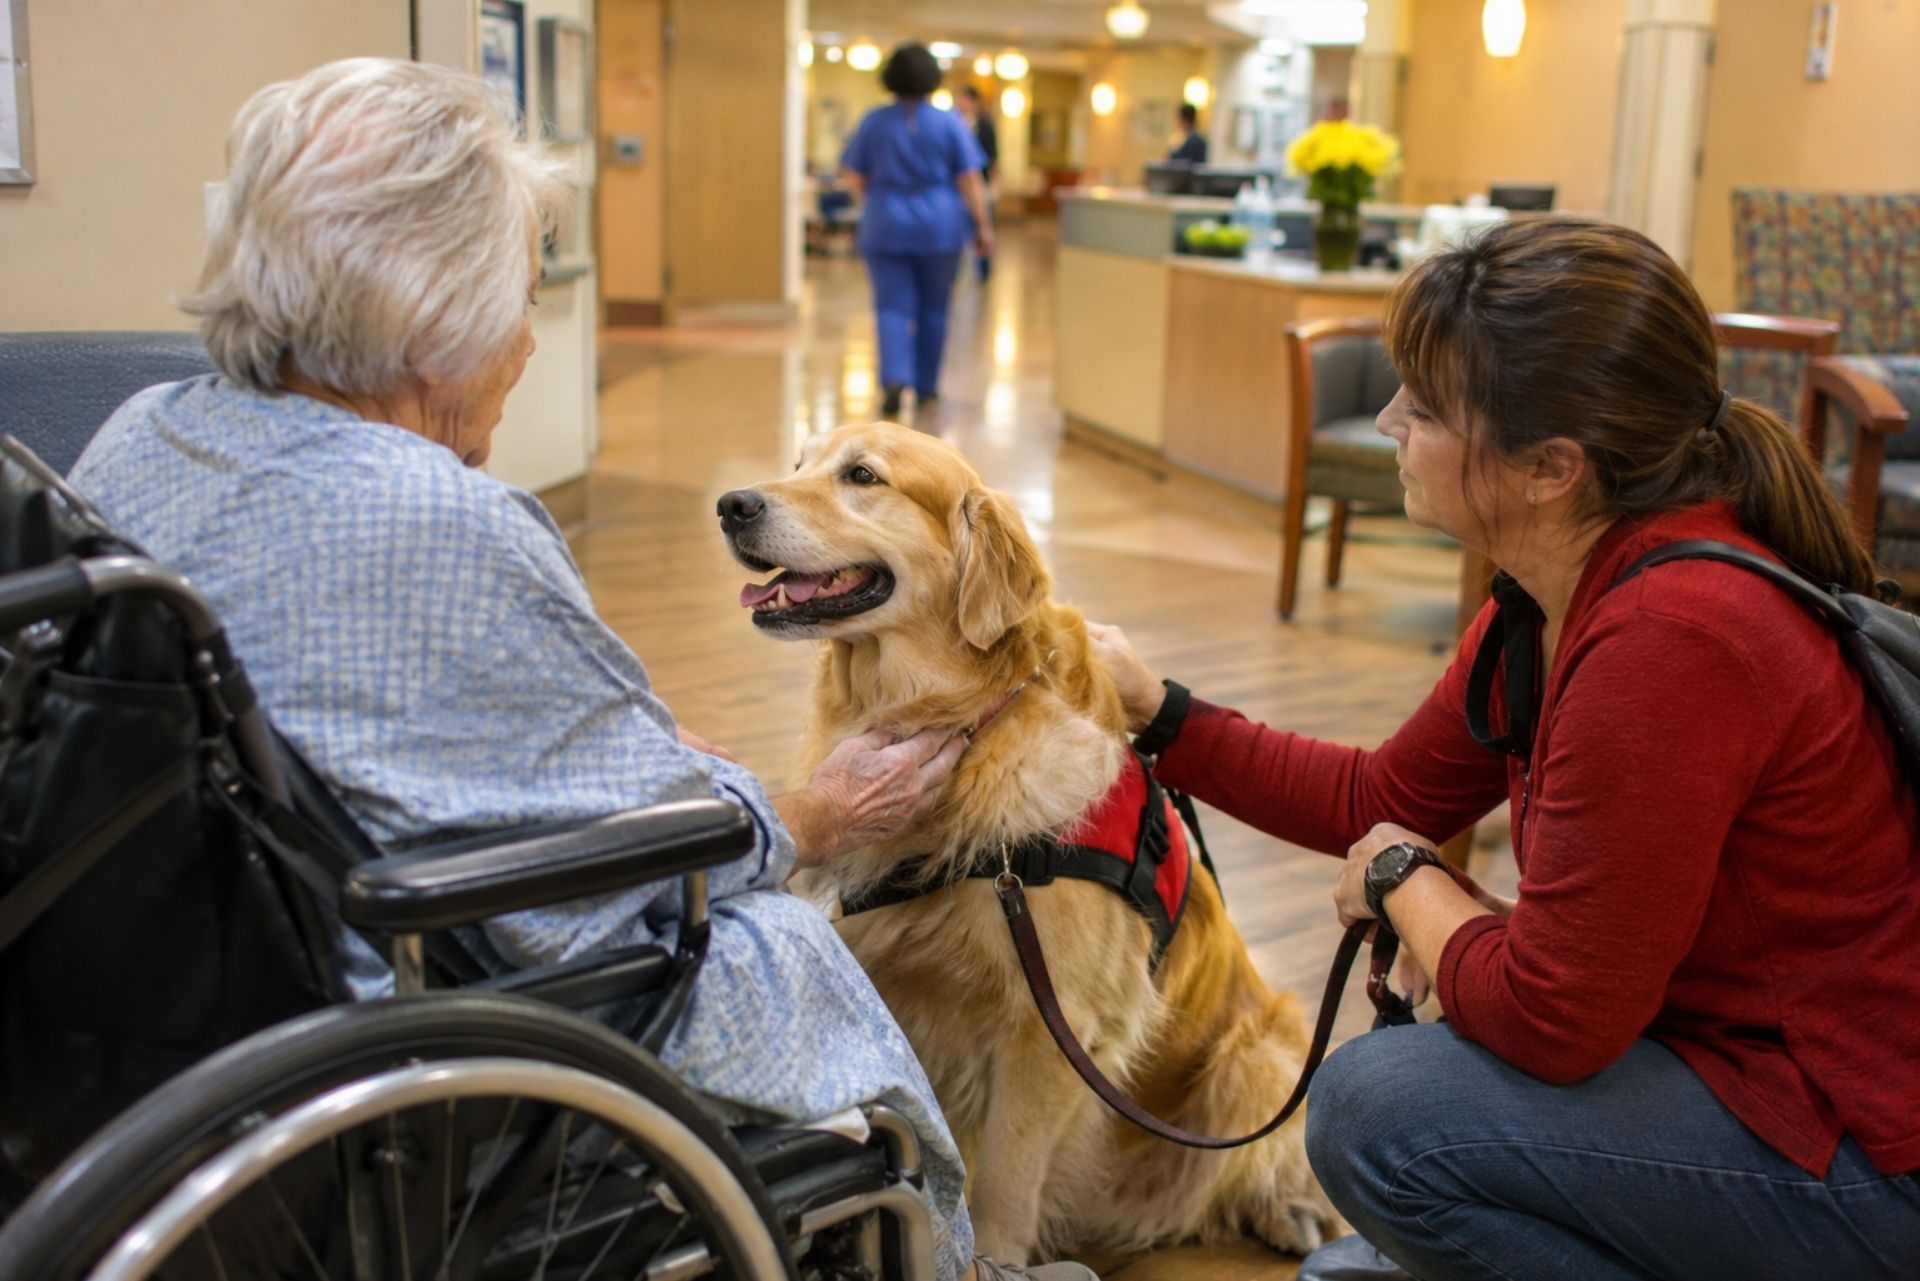
Picture a handler and her golden retriever on their weekly visit to a memory-care unit. A resident reaches out too fast, the dog startles, and an elderly woman falls and fractures her wrist. Within a month, the facility's insurer sends a letter asking who covers the medical bills. For therapy dog teams, that letter is the moment insurance stops being a formality.
Why Therapy Dog Handlers Need Liability Insurance
Hospitals, schools, and nursing homes almost always require visiting teams to carry their own coverage before they set foot inside. The facility's own policy protects the facility, not you. If a patient trips over a leash or a child gets nipped during a reading program, the injured party or their insurer can come after the handler personally.
Most claims we see in this space are not dramatic bites. They are trip-and-fall injuries, scratches on fragile skin, and allergic reactions. Even when the handler did nothing wrong, defense costs alone can run into thousands of dollars.
The good news is that many national therapy organizations bundle coverage into membership. For example, the Alliance of Therapy Dogs gives members a policy with $5,000,000 per occurrence and aggregate limits that covers all breeds. The catch is that this protection applies to registered, volunteer therapeutic visits. Once you charge a fee or fold therapy work into a paid business, you likely need your own commercial policy.
Comparing General Liability and Professional Liability Coverage
Handlers often assume one policy does everything. It doesn't. General liability and professional liability respond to very different problems, and a gap between them is one of the most common mistakes we see with trainers and pet professionals who add therapy visits to their services.
| Feature | General Liability | Professional Liability |
|---|---|---|
| Covers | Bodily injury, property damage | Errors in advice or services |
| Typical claim | Patient trips over the leash | Client says your training failed |
| Who needs it | Every visiting team | Paid trainers, evaluators |
| Defense costs | Usually included | Usually included |
One thing to keep in mind: bite claims are where policies get tricky. Some general liability forms exclude animal bites or cap them with a lower sublimit. Read the exclusions page before you sign. The organizational policy mentioned above, for instance, covers defense costs within the limit of liability, which means legal fees reduce the amount left for settlements.
Common Questions About Therapy Animal Protection
Does my homeowners policy cover therapy visits? Usually not, since visits happen away from your home and may count as business activity. Some homeowners carriers also restrict certain breeds, so check your policy wording.
Can my insurer drop me for having a therapy dog? It depends on your state. Connecticut lawmakers introduced a 2026 bill to stop insurers from denying homeowners coverage to owners of trained therapy or service animals, but most states have no such protection yet.
Is a therapy dog the same as a service animal legally? No. A May 2026 federal housing memo narrowed protections so that a housing request is presumed reasonable only when the animal is trained for disability-related tasks, which most therapy dogs are not.
What if someone sues because my dog got hurt? Courts generally treat pets as property. A 2026 New York appellate ruling reaffirmed that pets are personal property, which keeps damages focused on economic value rather than emotional distress.
Does coverage follow me across state lines? Many organizational policies do, but commercial policies vary. Confirm the territory listed on your declarations page.
Laws differ by state and change often, so talk with a qualified attorney about your specific situation.
Making the Right Choice for Your Visiting Team
Start by asking whether your visits are purely volunteer. If yes, organizational membership coverage may be enough, though you should still request a certificate of insurance to hand facilities. If you're a groomer, trainer, or daycare owner who brings dogs into schools or hospitals as part of your business, the volunteer policy probably won't respond.
Before you commit, check these points:
- Bite coverage: Is it included at full limits or sublimited?
- Care, custody, and control: Does it cover dogs in your care that aren't yours?
- Additional insured status: Will facilities you visit be named on the certificate?
- Professional services: Does it cover advice, evaluations, or training work?
This is where a specialist helps. Pet Professional Insurance Agency uses intake forms built for each pet-business type and shops your risk across multiple specialty insurance markets, so trainers and daycare owners get coverage that actually matches how their teams work in the field.
Index
Pet Professional Insurance Agency is fully licensed and permitted to provide commercial insurance solutions for pet businesses across 12 states.
We proudly serve pet professionals throughout the Northeast, Mid-Atlantic, and Southeast. Powered by Joyce Insurance Agency, our team works with leading specialty carriers — including The Hartford, USLI, Nautilus, and Northland — to make sure veterinarians, groomers, boarding facilities, and pet-care businesses receive coverage that fits their real risks in Connecticut, Delaware, Georgia, Kentucky, Massachusetts, New Jersey, New York, North Carolina, Pennsylvania, South Carolina, Tennessee, and Virginia.
About the author
Barnaby Joyce
Founder, Pet Professional Insurance Agency · Licensed Insurance Producer
I started Pet Professional Insurance Agency because I watched pet businesses get handed generic policies that never fit. After years of placing coverage for veterinary practices, grooming salons, doggy daycares, and kennels through a generalist agency, I saw the same gaps over and over — and the same blank stares when an owner tried to explain care, custody, and control to an agent who had never insured an animal in their life.
So I built an agency that does one thing. I work directly with specialty carriers who actually want pet-industry risk, and I sit down with every client personally. You will not get a call center or a chatbot. You will get someone who already speaks your language and shops the market on your behalf. That is the whole idea.
Related coverages
Coverages that pair with general liability.
Most pet businesses build on general liability with the lines below. Explore each — every page cross-links to the
industries we serve.
Services & advice
Professional Liability / E&O
Covers claims tied to your professional services and advice — clinical care, training guidance, and the judgment calls you make daily.
The pet-industry gap
Care, Custody & Control
Covers the animals in your charge against injury, illness, or loss — the critical exposure standard liability policies leave out.
Bundled & cost-effective
Business Owners Policy (BOP)
Bundles property and general liability into one package built for small to mid-sized pet businesses — often the simplest base.
Your building & contents
Commercial Property
Protects your building, build-out, equipment, and inventory against fire, theft, and covered losses — front desk to back room.
For your team
Workers’ Compensation
Covers medical costs and lost wages when a team member is hurt on the job — required in most states once you have employees.
Extra protection
Commercial Umbrella
Adds liability limits above your primary policies for catastrophic claims that exceed standard coverage.
Coverage availability and terms vary by carrier and state. We recommend the right mix for your operation once we talk.
Industries we serve
Built for the businesses that care for animals.
General liability is the baseline for every segment we specialize in. Find the page built for your business.
Clinical · high exposure
Veterinarians & Animal Hospitals
Professional and general liability, property, and workers’ comp for clinical operators with high exposure.
Hands-on · small business
Pet Groomers
Practical protection for animal handling, equipment, and the day-to-day of the grooming table, shop or mobile.
Safety-forward · overnight
Doggy Daycare & Boarding
Coverage matched to facilities responsible for animals overnight and all day long.
Our reviews
Trusted by pet professionals.
See what owners say about working with a specialist who already understands their business.
Frequently asked
Questions pet pros ask us.
What kinds of pet businesses do you insure?
We insure businesses across the animal-care industry — veterinarians and animal hospitals, groomers, doggy daycares and boarding facilities, kennels and trainers, pet sitters and dog walkers, and pet stores. We also cover breeders, equine operations, pet transporters, shelters and rescues, pet photographers, and aquariums or wildlife facilities.
If your work involves caring for, handling, or selling animals, there is a strong chance we cover it. Tell us what you do and we will confirm.
What is care, custody, and control coverage, and why does it matter?
Care, custody, and control coverage protects you when an animal in your charge is injured, becomes ill, or is lost while in your care. Standard general liability policies often exclude this exact exposure, which leaves a serious gap for pet businesses.
For groomers, boarders, sitters, and clinics, this is one of the most important coverages you can carry. We make sure it is in place and sized to your operation.
How is an independent agency different from buying direct from a carrier?
A direct carrier sells you its own single policy. As an independent agency, we shop multiple specialty insurers and compare programs to find the coverage that fits your business and budget.
That means you get options instead of one quote, and an advocate who works for you, not the carrier. We also handle the renewals and claims support over the life of your policy.
How fast can I get a quote?
Most clients get quoted within one business day. Our industry-specific intake forms collect the right details up front, so we can take your information straight to the carriers without a long back-and-forth.
Need it sooner? Call a specialist directly at (346) 738-7297 and we will move quickly.
Which states do you serve?
We are licensed and actively writing coverage in 12 states: Connecticut, Delaware, Georgia, Kentucky, Massachusetts, New Jersey, New York, North Carolina, Pennsylvania, South Carolina, Tennessee, and Virginia.
We continue to add states as we grow. If you operate outside this list, reach out and we will let you know our latest footprint.
From the blog
Coverage notes for pet professionals.
Plain-language risk tips and coverage explainers, written for owners — not insurance pros.
Speak with a specialist
Let's find the right coverage for your business.
No quote bots, no funnel. Talk to a real pet-insurance specialist who already understands your operation — and shops multiple markets on your behalf.
Call us
(346) 738-7297
Toll-free 845-250-5366
Email
service@petindustryins.com
Visit Us
8 Joyce Plaza
Stony Point, NY 10980