Coverage for veterinary practices
Rhode Island Pet Groomer Insurance
Core Protections Against Bodily Injury and Property Damage
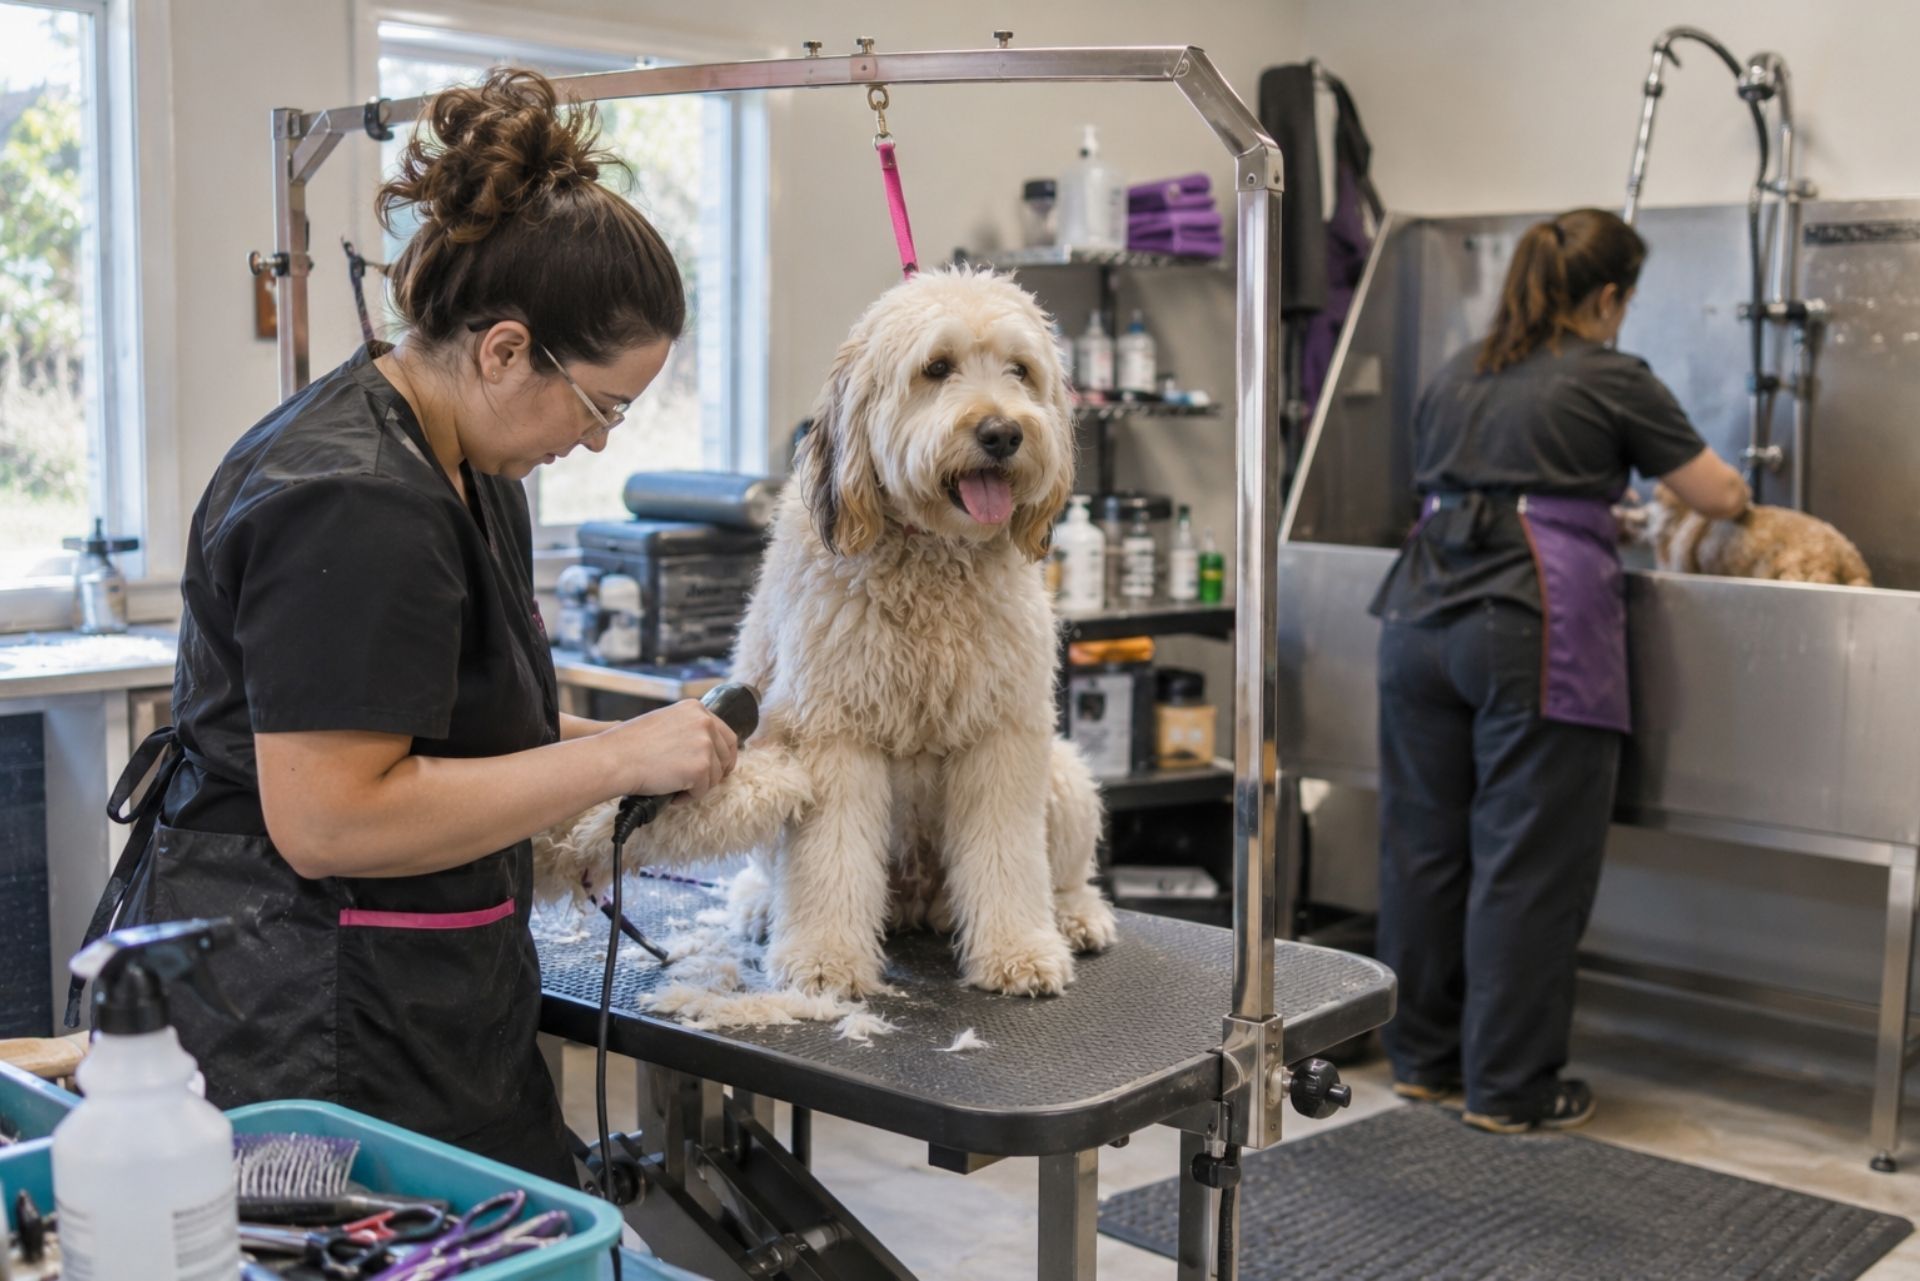
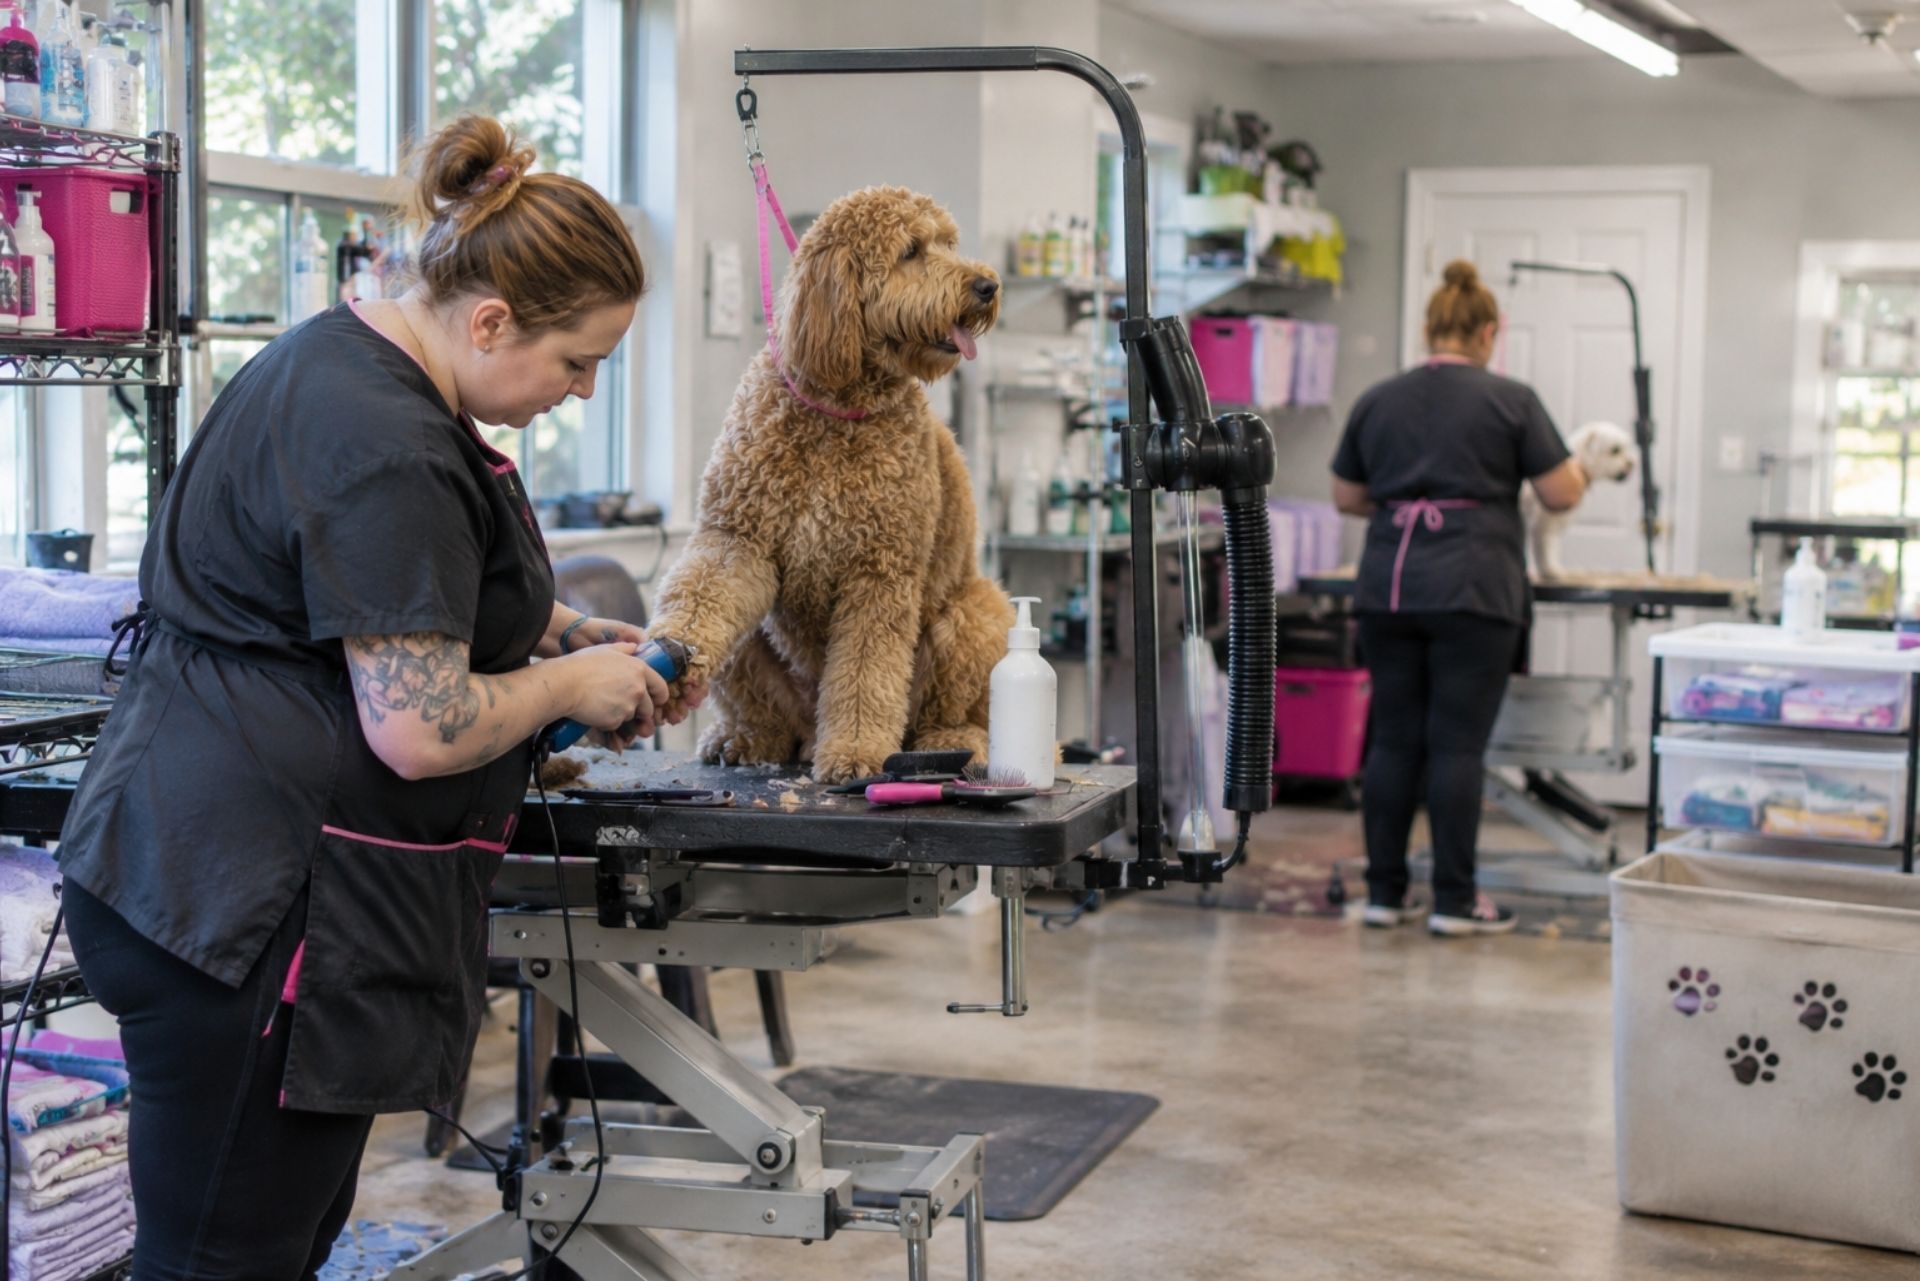
The groomer was trimming around a nervous doodle's ear when the dog jerked its head, and a small nick turned into a vet bill, an angry phone call, and a social media post by dinner time. Rhode Island groomers deal with versions of this story every year. The question is whether your insurance actually pays for it.
Most grooming policies look alike on the first page. They split apart in the fine print, especially around animals in your care. Pet groomer insurance in Rhode Island also has some state-specific wrinkles. The state takes a strict approach to dog bites, it enforces workers' comp rules for even one part-time bather, and 2026 legislation could raise the dollar value of a single injured pet.
This guide walks through general liability, animal bailee coverage, grooming injury claims, property, workers' compensation, and costs. The goal is for you to know which questions to ask before you sign anything.
Protecting Your Rhode Island Pet Grooming Business
A grooming business carries three kinds of risk: harm to animals, harm to people, and harm to your stuff. A dog that slips off a table, a client who trips over a hose in your lobby, and a burst pipe that ruins your tubs all need different coverage. Many new salon owners buy one general liability policy and assume they're covered for all three. They aren't.
The stakes in Rhode Island are climbing. Two bills introduced in April 2026, 2026-S 2151 and 2026-S 2397, would let pet owners sue for non-economic damages such as emotional distress when a pet is seriously injured or killed through negligence. Today, a claim for an injured dog is often limited to vet bills and the animal's market value. If those bills pass, a pet owner could also claim damages for grief or distress, which would push settlement amounts and defense costs higher.
None of this is settled law yet. It's still a good reason to check your limits now instead of after a claim.
Core Coverages: General Liability vs. Animal Bailee
These two coverages cause more confusion than anything else in a grooming policy. The short version is that general liability protects people and their property, and animal bailee protects the pets you're holding. Here's how each one works.
Understanding Animal Bailee for Grooming Injuries
"Bailee" means you have temporary custody of someone else's property, and legally a pet counts as property. Standard general liability policies usually exclude property in your "care, custody, or control." That exclusion is the reason a dog injured on your grooming table often isn't covered by GL alone.
Animal bailee coverage, sometimes called care, custody, and control coverage, fills that gap. Common grooming injury claims include:
- Clipper cuts and nicks, especially around ears, armpits, and sanitary areas
- Clipper burn and razor rash
- Falls from tables or escapes from grooming loops
- Heat injuries from cage or kennel dryers
- Injuries between dogs in shared holding areas
- A dog that bolts out the door and gets hit by a car
Check the per-animal limit as well as the aggregate. A policy might cap payouts at a low amount per pet, which won't stretch far if a purebred needs surgery. Some groomers also add professional liability (errors and omissions), which typically costs an extra $100 to $300 per year in Rhode Island. It responds to claims tied to your grooming judgment, such as a shave-down that a client says caused skin problems.
General Liability for Third-Party Accidents
General liability pays when someone who isn't your employee gets hurt, or when you damage property that isn't yours. Typical examples are a client slipping on a wet floor, a dog in your care biting a customer in the lobby, or a mobile groomer's van backing into a client's fence. (The fence damage depends on the policy. Some of that falls under commercial auto.)
Bite exposure matters a lot here. Rhode Island imposes strict liability for dog bites occurring outside the dog's enclosure, and a groomer holding the dog can be treated as its "keeper." Strict liability means the injured person may not have to prove you were careless. Make sure your GL policy doesn't carry an animal or bite exclusion. Some generic small-business policies do, and that is a serious problem for a groomer. Statutes can be interpreted in different ways, so talk to a Rhode Island attorney about your specific exposure.
Rhode Island Workers' Compensation and Property Requirements
Rhode Island requires every business with one or more employees, full-time or part-time, to carry workers' compensation. That includes the weekend bather and the teenager who sweeps up after school. Grooming is physical work. Bites, scratches, repetitive strain in the wrists and shoulders, and back injuries from lifting large dogs into tubs all show up regularly in workers' comp claims.
The most common mistake we see is calling helpers "independent contractors" to avoid buying a policy. Labels don't control how the state classifies a worker. If you set the hours, supply the tools, and direct the work, that person probably counts as an employee. Ask an employment attorney if the arrangement is unclear.
Property coverage isn't required by law, but your landlord or equipment lender will probably demand it. It protects things like:
- Hydraulic and electric grooming tables
- Tubs, dryers, and clippers
- Retail inventory such as shampoos and accessories
- Business income lost if a fire or water damage closes you down
Mobile groomers should know that equipment bolted into a van may need inland marine or specific auto endorsements. A standard property policy usually covers equipment only while it's at your location.
Comparing Basic and Comprehensive Grooming Insurance Plans
A "basic" policy usually means general liability and not much else. A comprehensive package bundles the coverages a working salon actually needs. Here's how they compare:
| Coverage | Basic Plan | Comprehensive Plan |
|---|---|---|
| General liability | Included | Included |
| Animal bailee | Often excluded or low limit | Included, higher per-animal limit |
| Professional liability (E&O) | Not included | Included or easy add-on |
| Business property | Not included | Included |
| Business income | Not included | Often included |
| Workers' comp | Separate policy | Separate policy, often coordinated |
| Best fit | Solo groomer testing the market | Salons, staff, mobile units |
Workers' comp is always written as its own policy, but a good agent will place it alongside your package so the coverages don't leave gaps or overlap.
Our advice is simple. If you put your hands on dogs for a living, a plan without animal bailee is a plan with a hole in the middle. The money you save on premium rarely makes up for paying a single surgery bill yourself.
Factors Influencing Insurance Costs in the Ocean State
Rhode Island isn't an inexpensive place to insure a grooming business. It ranks among the priciest states, with an average monthly cost of about $153 for a comprehensive policy. Your own costs will depend on:
- Payroll and number of employees, which drives workers' comp premiums
- Annual revenue and the number of grooms
- Claims history, especially past animal injury claims
- Limits and deductibles you choose
- Services offered, since hand-stripping, cat grooming, or add-on boarding raise the risk
- Location, because Providence storefronts usually cost more than suburban ones
Mobile Grooming vs. Brick-and-Mortar Expenses
Mobile groomers skip the property premium on a storefront, but they pick up commercial auto. A converted van with a generator, water tanks, and installed tables is expensive to insure, and personal auto policies generally won't cover business use. Equipment coverage also has to follow the vehicle.
Salons have the opposite profile. They carry more premises liability because clients walk in and out all day, and they need property and business income coverage for the building. They also tend to have more staff, which pushes workers' comp costs up. Neither model is automatically cheaper to insure. Compare the full package, not just the liability line.
Common Questions About Rhode Island Pet Insurance
Is general liability enough for a home-based groomer? Usually not. Homeowners policies tend to exclude business activity, and GL alone typically excludes injuries to pets in your care.
Do I need workers' comp if my only employee is part-time? Yes. Rhode Island requires coverage once you have even one employee, full-time or part-time.
Does my policy cover a dog that bites me? If you're the owner and have no workers' comp policy covering yourself, probably not. Many owners choose to include themselves on workers' comp for that reason.
How fast can I get coverage in place? With a specialty agency, often within a few days. Pet Professional Insurance Agency clients usually hear back within 24 to 48 hours.
Will Rhode Island's new pet insurance law affect me? The 2026 consumer pet insurance act targets companies that sell pet health insurance to owners, not groomers. Supporters argue it will protect pet owners by requiring insurers to provide detailed coverage information. The separate damages bills are more likely to affect your liability.
What's the most common grooming claim? Cuts and nicks from clippers or scissors, followed by falls and dryer-related heat injuries.
Making the Right Choice for Your Salon
Rhode Island groomers face strict bite liability, required workers' comp for any staff, above-average premiums, and pending legislation that could make injured-pet claims more costly. A policy built for a generic retail shop won't hold up under those conditions. Animal bailee coverage, a GL policy with no animal exclusion, and limits that fit the 2026 legal climate should be your starting point.
Before you renew, pull out your current declarations page. Check three things: the per-animal bailee limit, any bite or animal exclusions, and whether your workers' comp classification matches what your staff actually do.
Pet Professional Insurance Agency works only with pet-care businesses. We use intake forms built specifically for groomers and compare options across multiple specialty insurance markets, and you work directly with your agent the whole way through. Reach out to get your coverage reviewed. The time to find a gap in your policy is before a nervous doodle finds it for you.
Index
Pet Professional Insurance Agency is fully licensed and permitted to provide commercial insurance solutions for pet businesses across 12 states.
We proudly serve pet professionals throughout the Northeast, Mid-Atlantic, and Southeast. Powered by Joyce Insurance Agency, our team works with leading specialty carriers — including The Hartford, USLI, Nautilus, and Northland — to make sure veterinarians, groomers, boarding facilities, and pet-care businesses receive coverage that fits their real risks in Connecticut, Delaware, Georgia, Kentucky, Massachusetts, New Jersey, New York, North Carolina, Pennsylvania, South Carolina, Tennessee, and Virginia.
About the author
Barnaby Joyce
Founder, Pet Professional Insurance Agency · Licensed Insurance Producer
I started Pet Professional Insurance Agency because I watched pet businesses get handed generic policies that never fit. After years of placing coverage for veterinary practices, grooming salons, doggy daycares, and kennels through a generalist agency, I saw the same gaps over and over — and the same blank stares when an owner tried to explain care, custody, and control to an agent who had never insured an animal in their life.
So I built an agency that does one thing. I work directly with specialty carriers who actually want pet-industry risk, and I sit down with every client personally. You will not get a call center or a chatbot. You will get someone who already speaks your language and shops the market on your behalf. That is the whole idea.
Related coverages
Coverages that pair with general liability.
Most pet businesses build on general liability with the lines below. Explore each — every page cross-links to the
industries we serve.
Services & advice
Professional Liability / E&O
Covers claims tied to your professional services and advice — clinical care, training guidance, and the judgment calls you make daily.
The pet-industry gap
Care, Custody & Control
Covers the animals in your charge against injury, illness, or loss — the critical exposure standard liability policies leave out.
Bundled & cost-effective
Business Owners Policy (BOP)
Bundles property and general liability into one package built for small to mid-sized pet businesses — often the simplest base.
Your building & contents
Commercial Property
Protects your building, build-out, equipment, and inventory against fire, theft, and covered losses — front desk to back room.
For your team
Workers’ Compensation
Covers medical costs and lost wages when a team member is hurt on the job — required in most states once you have employees.
Extra protection
Commercial Umbrella
Adds liability limits above your primary policies for catastrophic claims that exceed standard coverage.
Coverage availability and terms vary by carrier and state. We recommend the right mix for your operation once we talk.
Industries we serve
Built for the businesses that care for animals.
General liability is the baseline for every segment we specialize in. Find the page built for your business.
Clinical · high exposure
Veterinarians & Animal Hospitals
Professional and general liability, property, and workers’ comp for clinical operators with high exposure.
Hands-on · small business
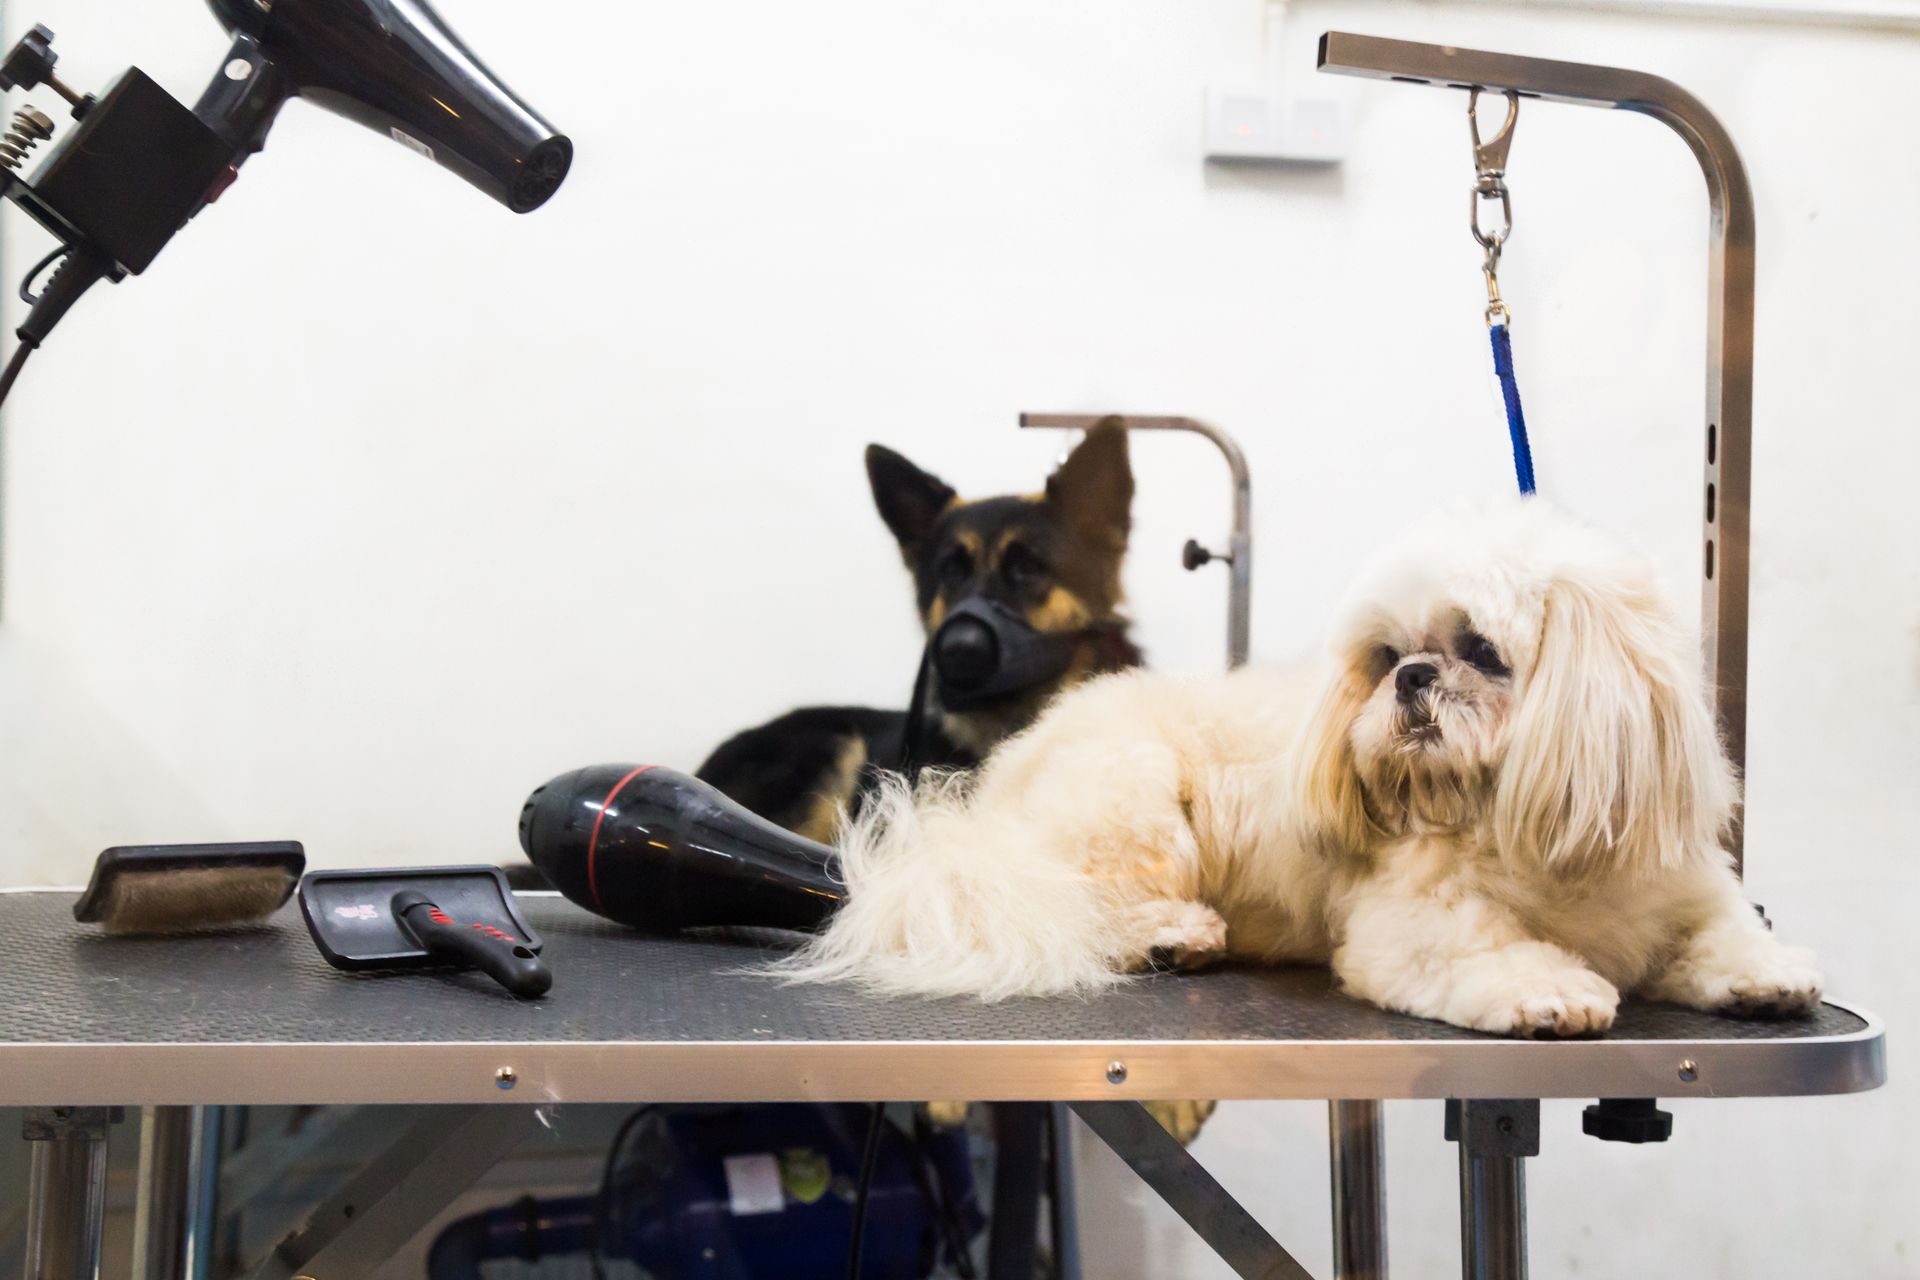
Pet Groomers
Practical protection for animal handling, equipment, and the day-to-day of the grooming table, shop or mobile.
Safety-forward · overnight
Doggy Daycare & Boarding
Coverage matched to facilities responsible for animals overnight and all day long.
Our reviews
Trusted by pet professionals.
See what owners say about working with a specialist who already understands their business.
Frequently asked
Questions pet pros ask us.
What kinds of pet businesses do you insure?
We insure businesses across the animal-care industry — veterinarians and animal hospitals, groomers, doggy daycares and boarding facilities, kennels and trainers, pet sitters and dog walkers, and pet stores. We also cover breeders, equine operations, pet transporters, shelters and rescues, pet photographers, and aquariums or wildlife facilities.
If your work involves caring for, handling, or selling animals, there is a strong chance we cover it. Tell us what you do and we will confirm.
What is care, custody, and control coverage, and why does it matter?
Care, custody, and control coverage protects you when an animal in your charge is injured, becomes ill, or is lost while in your care. Standard general liability policies often exclude this exact exposure, which leaves a serious gap for pet businesses.
For groomers, boarders, sitters, and clinics, this is one of the most important coverages you can carry. We make sure it is in place and sized to your operation.
How is an independent agency different from buying direct from a carrier?
A direct carrier sells you its own single policy. As an independent agency, we shop multiple specialty insurers and compare programs to find the coverage that fits your business and budget.
That means you get options instead of one quote, and an advocate who works for you, not the carrier. We also handle the renewals and claims support over the life of your policy.
How fast can I get a quote?
Most clients get quoted within one business day. Our industry-specific intake forms collect the right details up front, so we can take your information straight to the carriers without a long back-and-forth.
Need it sooner? Call a specialist directly at (346) 738-7297 and we will move quickly.
Which states do you serve?
We are licensed and actively writing coverage in 12 states: Connecticut, Delaware, Georgia, Kentucky, Massachusetts, New Jersey, New York, North Carolina, Pennsylvania, South Carolina, Tennessee, and Virginia.
We continue to add states as we grow. If you operate outside this list, reach out and we will let you know our latest footprint.
From the blog
Coverage notes for pet professionals.
Plain-language risk tips and coverage explainers, written for owners — not insurance pros.
Speak with a specialist
Let's find the right coverage for your business.
No quote bots, no funnel. Talk to a real pet-insurance specialist who already understands your operation — and shops multiple markets on your behalf.
Call us
(346) 738-7297
Toll-free 845-250-5366
Email
service@petindustryins.com
Visit Us
8 Joyce Plaza
Stony Point, NY 10980